Reddit (RDDT) Stock: Users Shrink as US ARPU Jumps 53%
Contents
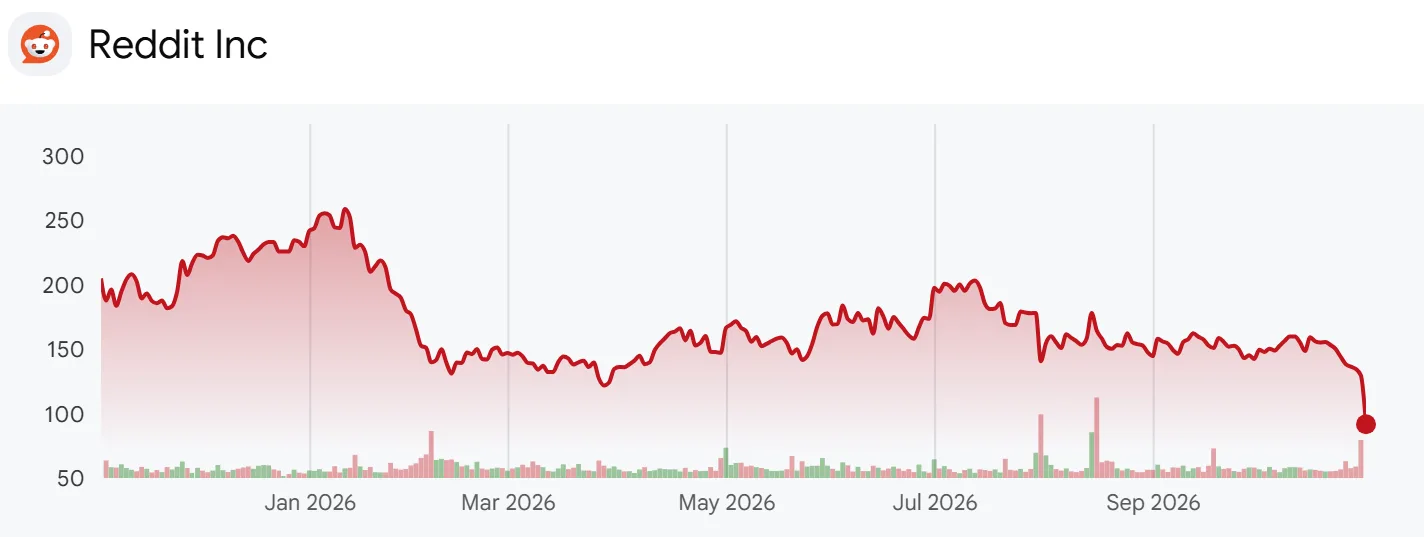
- Reddit (NYSE: RDDT) grew third-quarter revenue +53.0% to $895.0 million, then told shareholders that if October’s search trends continue, “current trends would suggest that total DAUqs could fall in Q4, by a low-double-digit percentage from our current base of 130 million DAUqs”. DAUq counts unique users who visit at least once a day. The stock fell -29.2% the next trading day, and the October month-end close of $91.73 sits -60.1% below the September 2025 month-end high of $229.99. Revenue now comes from revenue per user rather than user growth: US DAUq fell -1.7% year over year to 50.7 million while US ARPU rose +52.9% to $13.82.
- Reddit runs a network of interest-based communities called subreddits, where people post and comment under pseudonyms. Advertising was 94.6% of Q3 revenue, and most of the rest is content licensing, which sells access to Reddit’s posts and comments. At a $91.73 close it is worth about $17.7 billion on market data.
- The question here is how far ARPU gains can carry revenue while search-referred users fall away. The analysis lines up the Q3 2026 earnings release, the Q3 and Q2 2026 shareholder letters on the IR site, the Q3 2026 10-Q and all 11 quarterly earnings releases since the IPO.
- Two caveats apply. DAUq and ARPU are company-defined user metrics, not audited figures, and adjusted EBITDA and free cash flow are non-GAAP measures. User figures for 2023 come from the prior-year columns of the 2024 earnings releases.
What the Q3 Shareholder Letter Says About Search Traffic
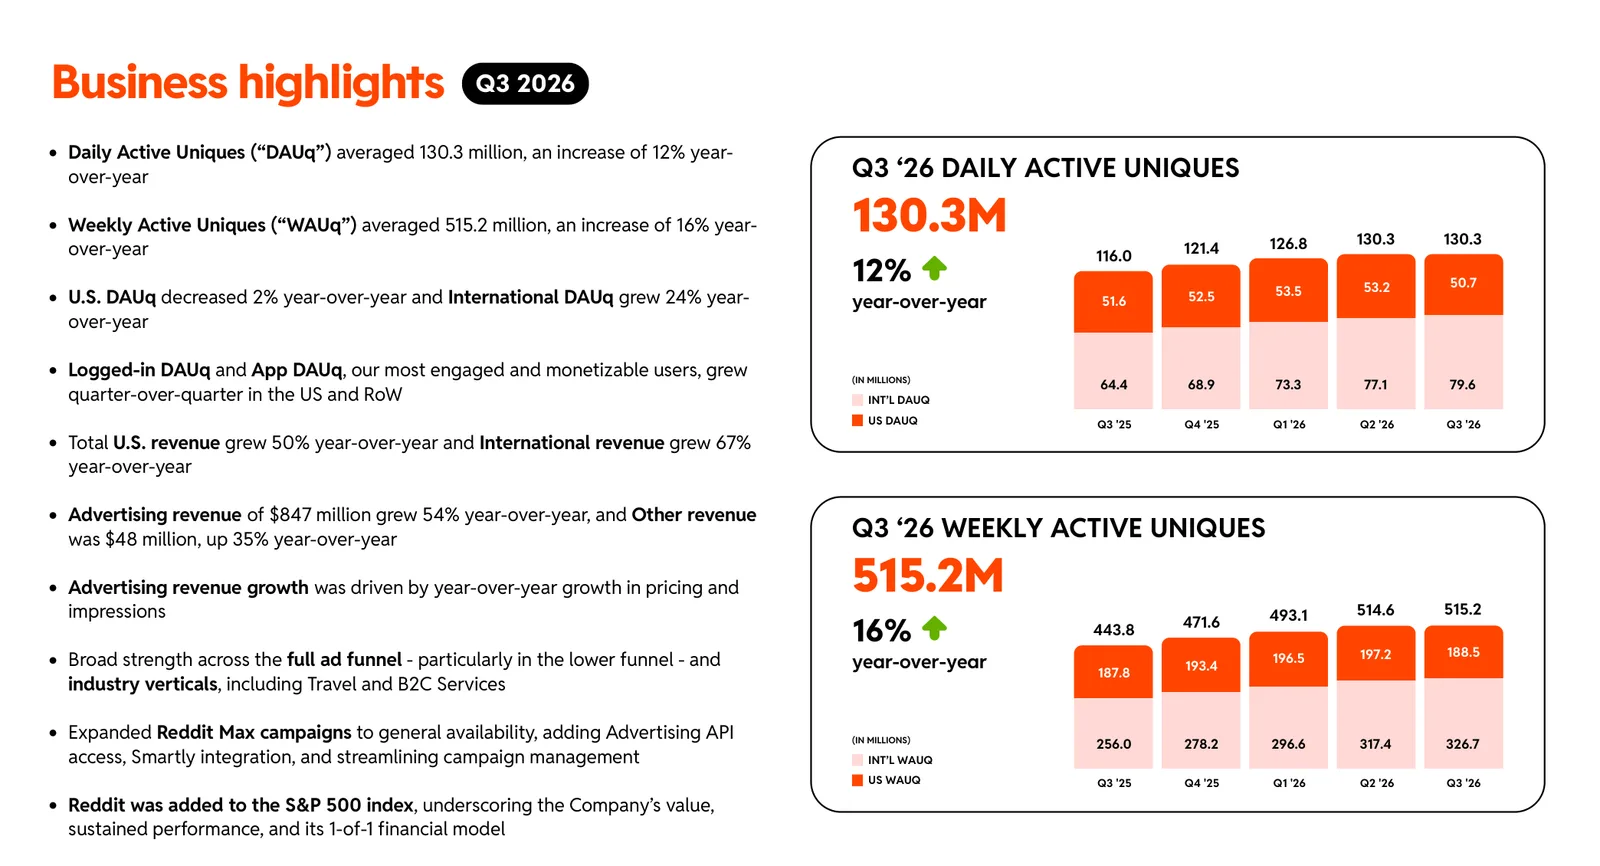
- The Q3 letter runs 21 pages. The page 3 business highlights lead with 130.3 million DAUq (+12%) and 515.2 million weekly active uniques, or WAUq (+16%). The bar chart on the same page shows US DAUq at 53.5 million in Q1 2026, 53.2 million in Q2 and 50.7 million in Q3, two straight sequential declines, while international DAUq of 79.6 million (+24%) held the total flat. The weekly chart below it shows US WAUq falling to 188.5 million from 197.2 million in Q2, roughly where it stood a year earlier at 187.8 million. The page also notes that logged-in and app users grew sequentially in the US and the rest of the world, and it presents the S&P 500 inclusion as proof of “its 1-of-1 financial model”.
- Company disclosure (Q3 2026 shareholder letter, October 29, 2026): In the page 4 letter, CEO Steve Huffman wrote, “Our search referral traffic was down meaningfully in Q3, with the decline accelerating later in the quarter.” The biggest hit was to logged-out and web traffic, and during October search traffic dropped by more than 1 million referrals a week on average. The Q2 letter had covered the same subject in one line: “Search referrals were choppy in the quarter, and traffic was more volatile later in the quarter”.
- Page 5 answers back. Logged-in and app users make up the vast majority of engagement and “over 80% of the monetization on Reddit”, and both grew from the prior quarter. The share of new app users who return in their first week is up double digits quarter over quarter and more than 50% year over year. “Currently only about 13% of eligible mobile web users are seeing the app conversion prompt”, the letter adds, so there is room to move more web visitors into the app. In Q4 the company will begin testing a logged-in-only Reddit in select markets outside the US.
- Checked against the releases, the two messages describe the same numbers from different sides. Global logged-in DAUq reached 53.5 million, up from 50.2 million a year earlier, but US logged-in DAUq of 23.4 million is barely above the 23.0 million of Q1 2025. International DAUq added 15.2 million in a year and covered the 0.9 million lost in the US, and most of the logged-in growth the letter cites came from outside the US.
Margin Trends and Share Count in the Q3 Letter
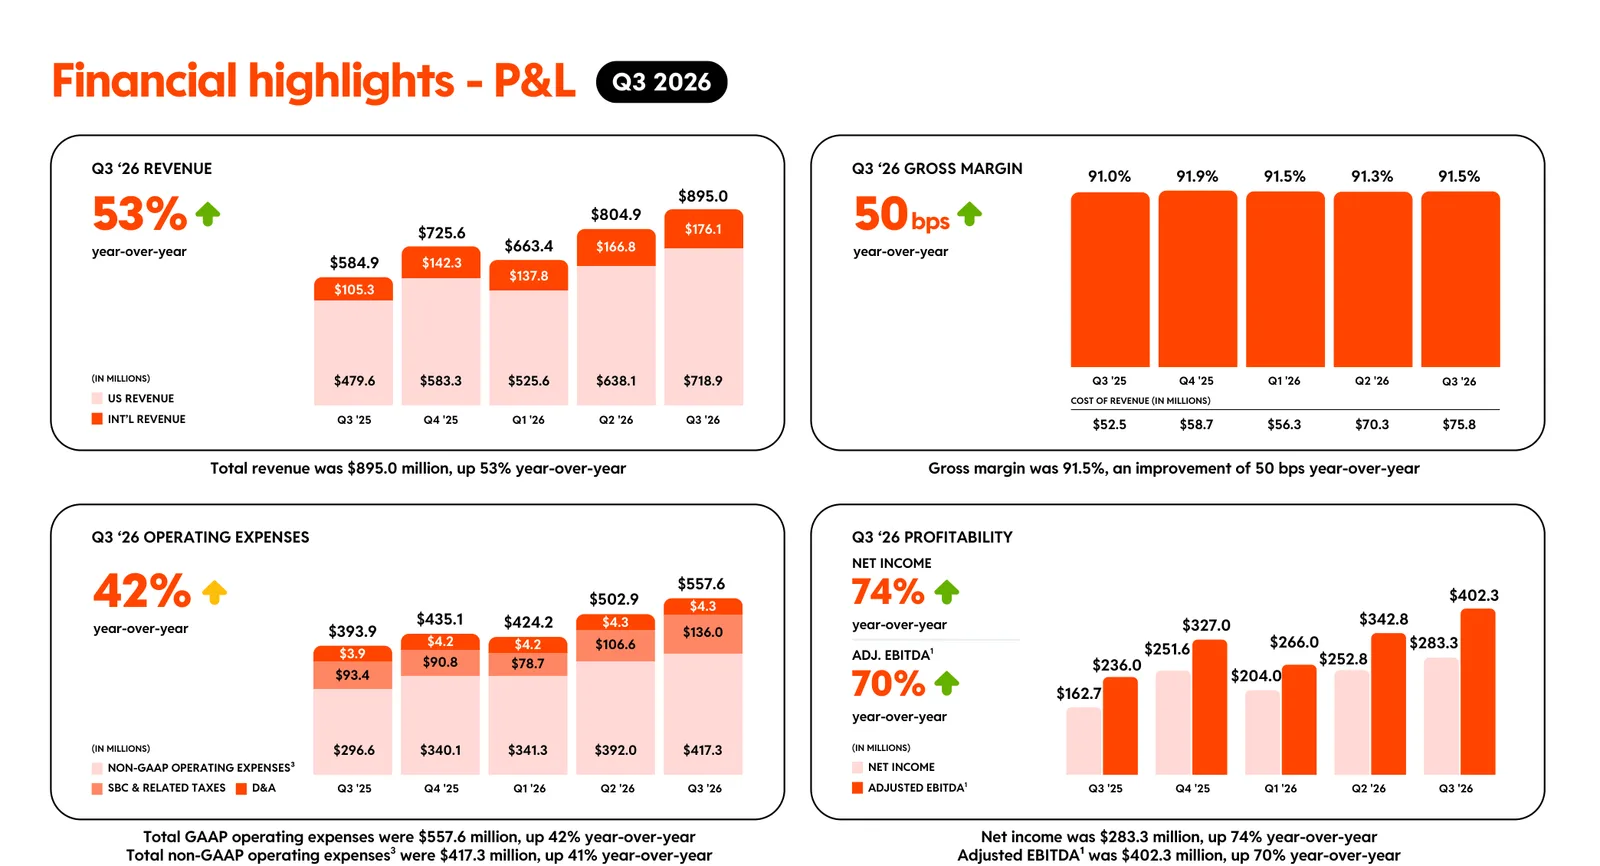
- Page 8 splits revenue into $718.9 million from the US (+50%) and $176.1 million internationally (+67%), with a 91.5% gross margin, net income of $283.3 million (+74%) and adjusted EBITDA of $402.3 million (+70%). Advertising revenue of $847 million grew +54%, which the letter attributes to higher pricing and more impressions. Diluted EPS was $1.40 (+75%) and capex was $1 million. GAAP operating expenses of $557.6 million and non-GAAP operating expenses of $417.3 million differ by $140.3 million, of which $136.0 million is stock-based compensation and related taxes in the page 8 chart.
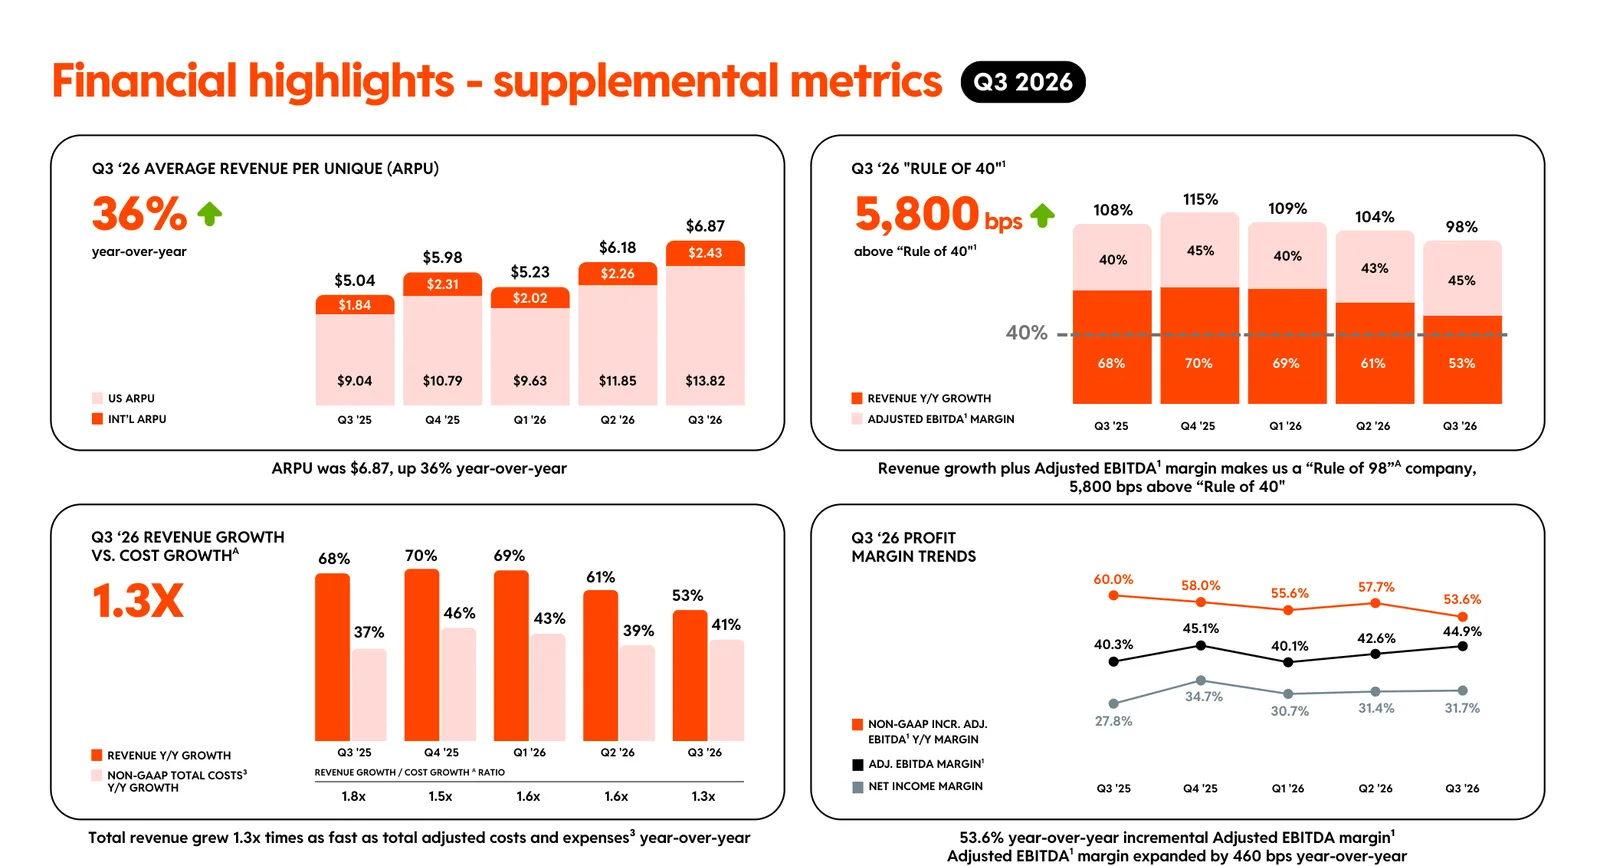
- Page 9 is where the slowdown shows. Revenue growth divided by cost growth fell from 1.8 times in Q3 2025 to 1.3 times in Q3 2026, and the incremental adjusted EBITDA margin, the share of each new dollar of revenue that reached adjusted EBITDA, slipped from 60.0% to 53.6%. Revenue growth itself went from 68% to 53%. The adjusted EBITDA margin of 44.9% is still 4.6 points higher than a year ago, but costs are catching up with revenue faster.
- The top-right chart calls Reddit a Rule of 98 company, adding revenue growth to adjusted EBITDA margin, 58 points above the usual threshold of 40. That sum has fallen three quarters in a row, from 115 in Q4 2025 to 109, 104 and 98, and nearly all of the drop is in growth while the margin has stayed between 40% and 45%. The ARPU chart leads with global ARPU of $6.87 (+36%), but over the year US ARPU rose $4.78 while international ARPU rose $0.59.
- Own calculation (Q3 2026 10-Q): Sales and marketing expense rose +62.7% to $209.4 million, faster than revenue, and took 23.4% of revenue against 22.0% a year earlier. The 10-Q attributes most of it to user and brand marketing and explains flat global DAUq as marketing gains that were “offset predominantly by third-party search engine changes”. Holding the user count steady now shows up as a cost.
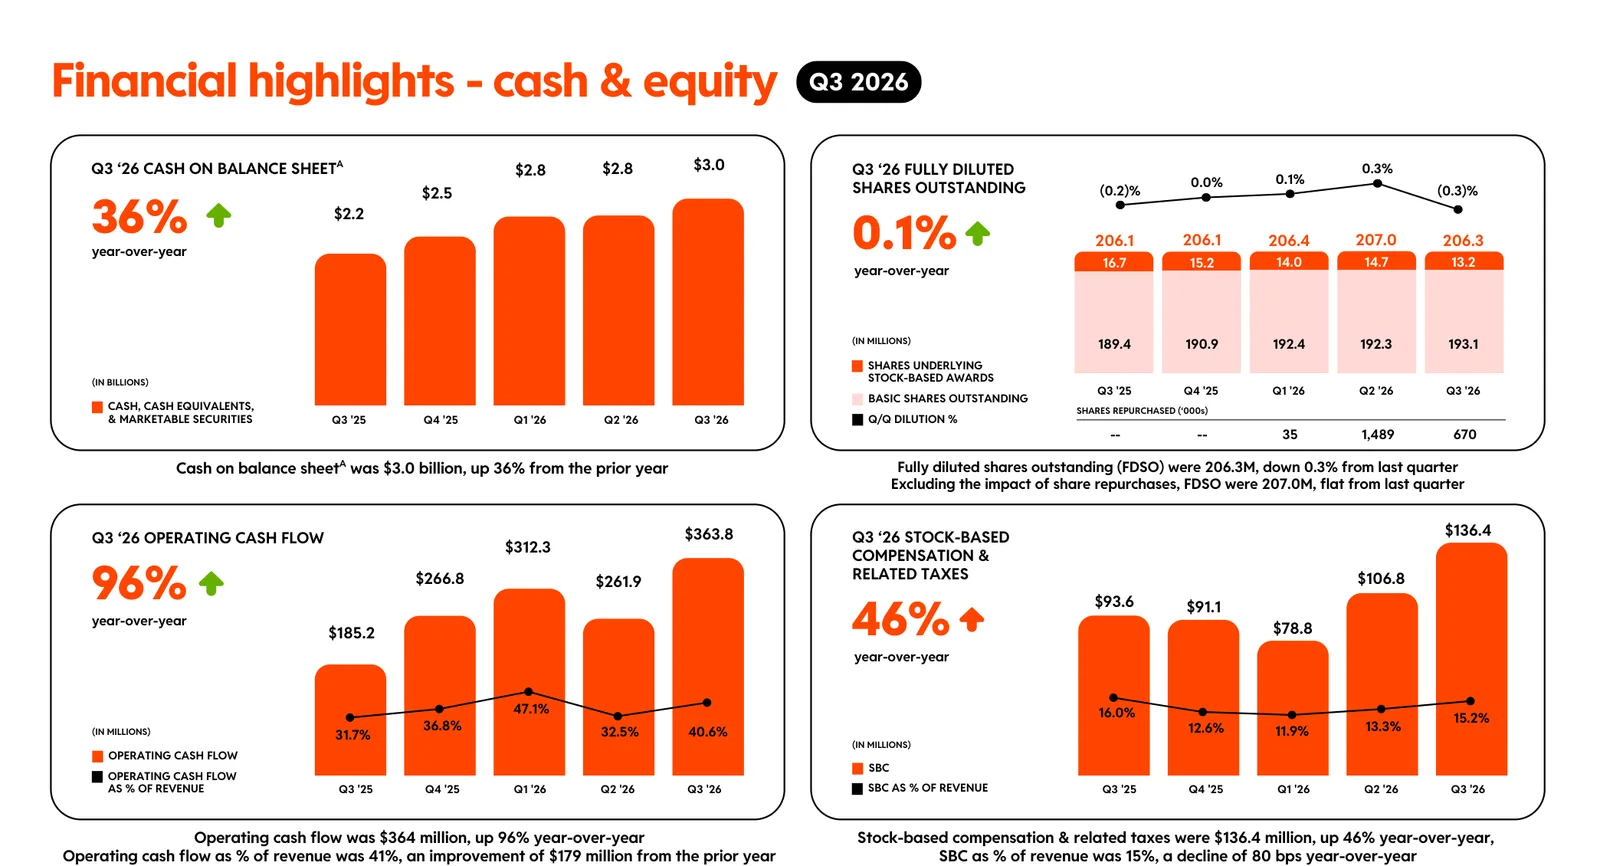
- Page 10 covers shares and cash. Fully diluted shares fell -0.3% to 206.3 million, or stayed flat at 207.0 million excluding buybacks. The same chart shows 35,000 shares repurchased in Q1 2026, 1.489 million in Q2 and about 670,000 in Q3, the last for $100 million at an average of $149.81. Stock-based compensation and related taxes were $136.4 million (+46%), or 15% of revenue. Cash and marketable securities stood at $3.0 billion, 36% more than a year earlier, and operating cash flow was 40.6% of revenue.
The Bull and Bear Case for Reddit Shares
- The bull case is that the users who pay the bills are holding up. Logged-in and app users, the source of over 80% of monetization, grew sequentially, and US ARPU growth more than covered the US user decline to lift US revenue +49.9%. Net margin is 31.7%, and the company holds $3.033 billion of cash and securities with no borrowings.
- The bear case is a shrinking audience. Management itself has warned of a Q4 DAUq decline, the Q3 revenue beat over guidance was the smallest in ten quarters, and Q4 revenue guidance implies growth of +37.8% to +42.0% against 53% in Q3, while user marketing grows faster than revenue.
From the 2024 IPO to the Q4 User Warning
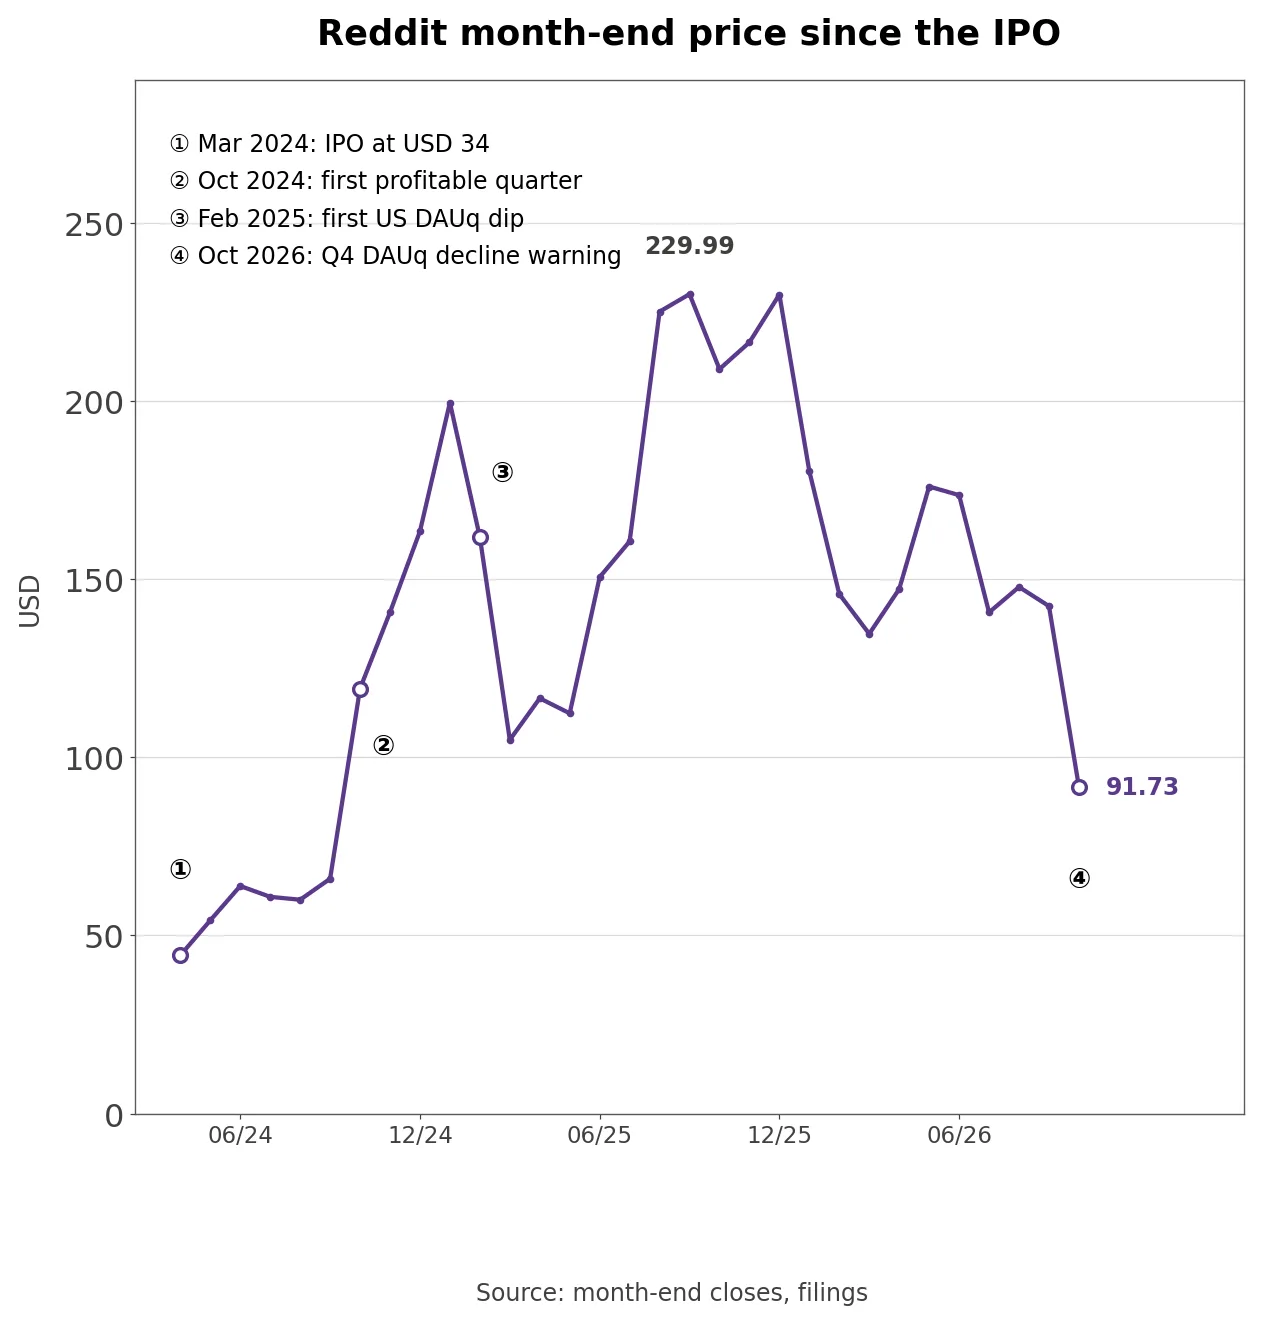
- Reddit, founded 21 years ago, completed its IPO on March 25, 2024, selling 25.3 million Class A shares at $34.00. IPO-related charges produced a $575.1 million net loss in Q1 2024. The company reported its first profit as a public company in Q3 2024, net income of $29.9 million, and the October 2024 month-end close jumped +81.0% to $119.30.
- The first user warning came in February 2025. US DAUq slipped from 48.2 million to 48.0 million in Q4 2024, the first sequential decline since the IPO, and the stock fell -47.4% from $199.55 at the end of January to $104.90 at the end of March. Q2 2025 revenue growth of +77.7% sent it +40.2% higher in August to $225.08, and September’s $229.99 is the post-IPO month-end high.
- The user problem returned in 2026. US DAUq peaked at 53.5 million in Q1, and Q3’s 50.7 million is the first year-over-year decline in the 11 quarters since Q1 2024. Reddit joined the S&P 500 in 2026, but after the Q4 DAUq warning the October close of $91.73 was -35.6% below September’s. That is still +169.8% above the IPO price.
How Many Reddit Users Arrive From Search?
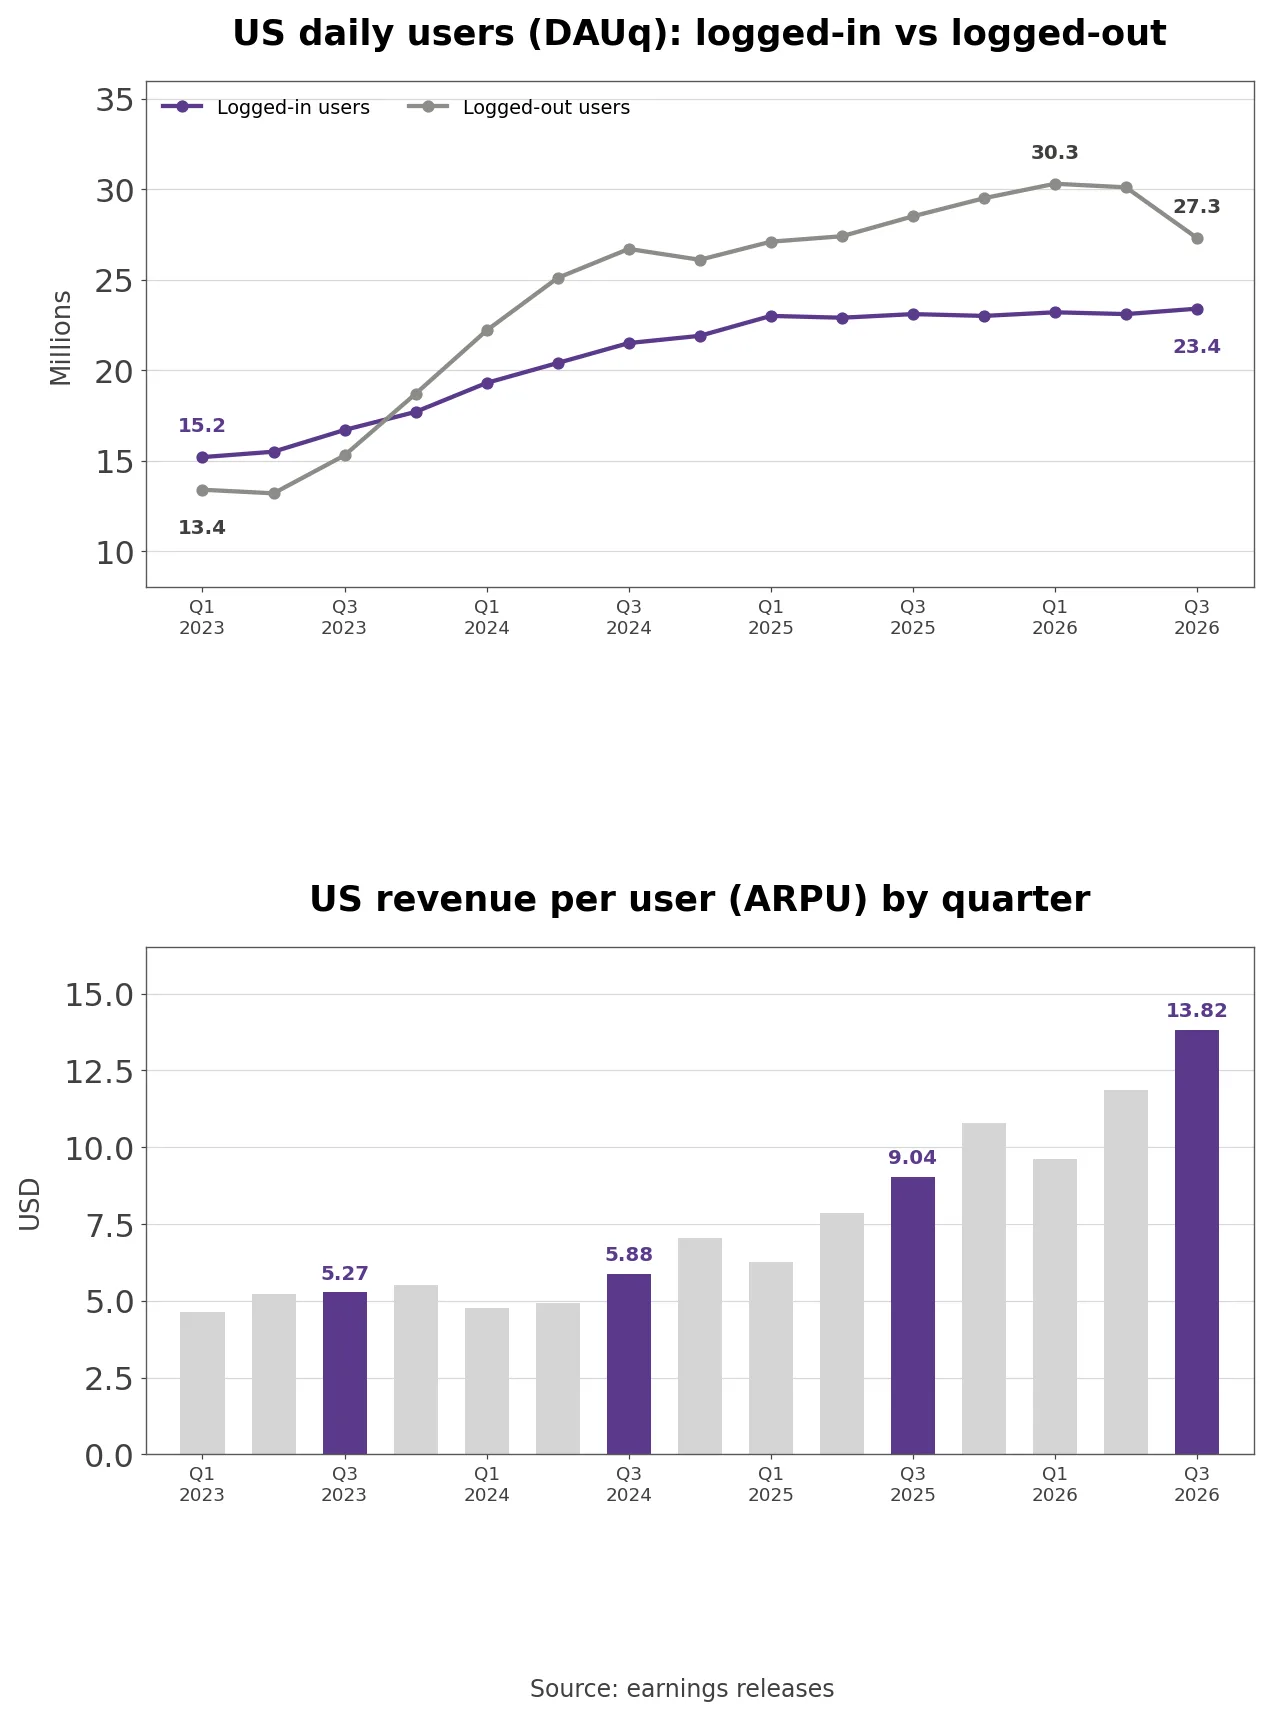
- Reddit splits DAUq into logged-in and logged-out users. Logged-out visitors often arrive from search results on the web, which is why the letter says the search decline hit logged-out and web traffic hardest. US logged-out DAUq rose from 13.4 million in Q1 2023 to 30.3 million in Q1 2026, then fell to 27.3 million in Q3, -9.9% from Q1 and -4.2% year over year. US logged-in DAUq grew from 15.2 million to 23.4 million over the same span but has stayed between 22.9 million and 23.4 million for the seven quarters since Q1 2025.
- Own calculation (11 quarterly earnings releases): Logged-out users are 53.8% of US DAUq and 58.9% of global DAUq, or 76.8 million of 130.3 million. With logged-out users in the majority, a drop in search referrals hits the headline user count first. Since logged-in and app users generate over 80% of monetization, users outside that group make up a large share of DAUq and less than 20% of monetization.
- The disclosure itself changed. In its 2025 10-K, Reddit said it would stop reporting logged-in and logged-out DAUq as of the quarter ended September 30, 2026. The Q3 10-Q kept them, citing increased volatility in referral traffic as third-party search changes, including AI-generated summaries and overviews, and saying “management believes that logged-in and logged-out DAUq remain useful for understanding user trends”. The split the company planned to drop came back in the quarter logged-out users started to fall.
US ARPU and the Shrinking Guidance Beat
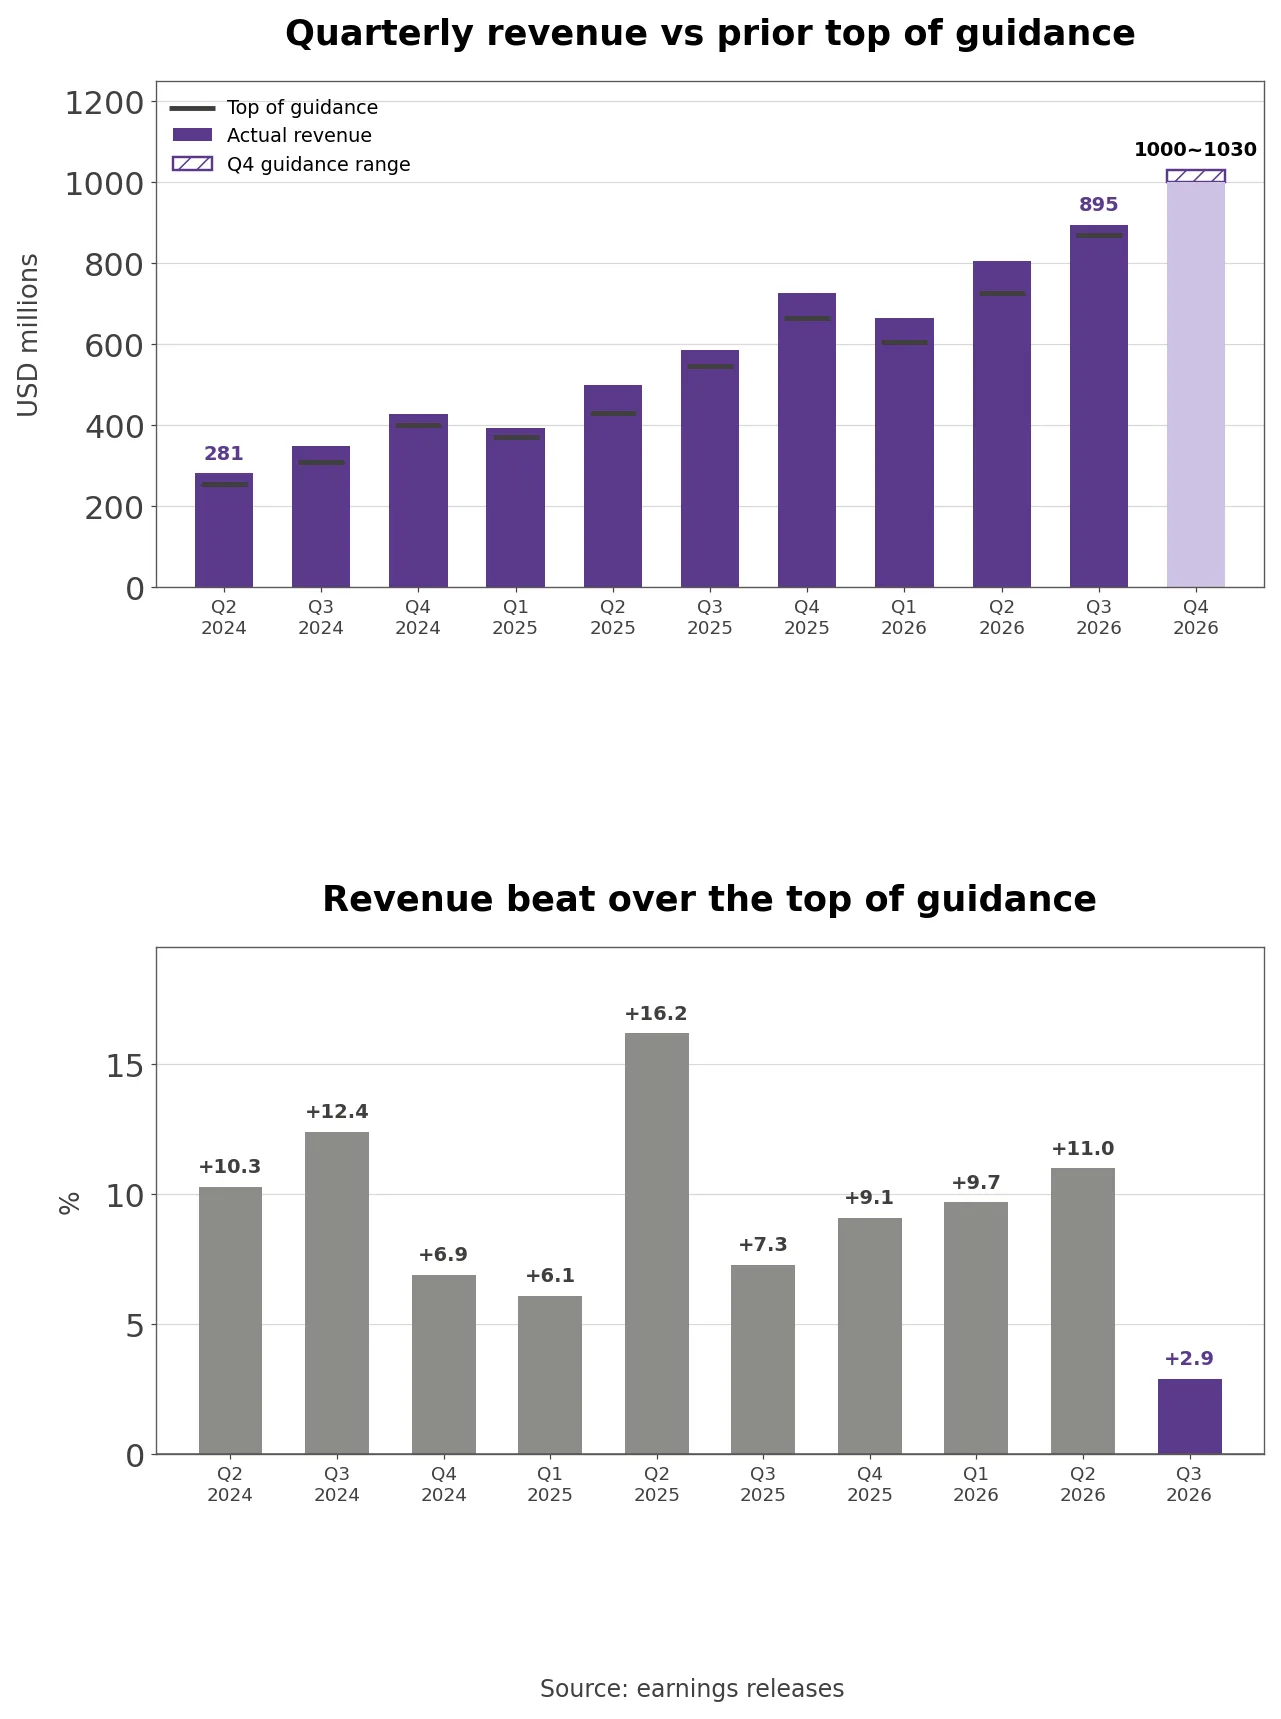
- Revenue came from ARPU, not users. Comparing third quarters, US ARPU went from $5.27 in 2023 to $5.88 in 2024, $9.04 in 2025 and $13.82 in 2026. US revenue growth of +49.9% is ARPU growth of +52.9% covering a -1.7% user decline, and US ARPU is 5.7 times international ARPU of $2.43. International ARPU rose +32.1%, but the gap with the US widened from 4.6 times in Q3 2023.
- The guidance record shows the slowdown. Revenue has beaten the top of the prior quarter’s guidance for ten straight quarters since Q2 2024, by as much as +16.2% in Q2 2025 and by as little as +2.9% in Q3 2026, against guidance of $860 million to $870 million. The previous smallest beat was +6.1% in Q1 2025.
- Own calculation (Q3 2026 letter and earnings releases): Q4 revenue guidance of $1.000 billion to $1.030 billion is +37.8% to +42.0% above the $725.6 million of Q4 2025. Reading the letter’s low-double-digit decline as -10% to -13% from Q3 puts Q4 DAUq at 113.4 million to 117.3 million. To meet guidance with that audience, Q4 global ARPU has to reach $8.53 to $9.09, +24.1% to +32.3% above Q3’s $6.87. Last year’s seasonal Q3 to Q4 ARPU increase was +18.7%.
- Q4 is the holiday ad season, so ARPU always rises, but this guidance needs 5 to 14 points more than last year’s seasonal step. It embeds management’s view that pricing gains will outrun the user decline.
How Reddit Makes Money
- Reddit is a platform of subreddits that users create and run. The 2025 10-K counts more than 100,000 active communities, and the CEO letter pitches Reddit as the place to read other people’s lived experiences without revealing a real-world identity. Users added another billion posts and comments in Q3. Moderators run individual communities with AI-powered tools from the company, and Reddit’s own enforcement team cut the median time to act on violating content from 58 hours to 5 seconds this year.
- Advertising is 94.6% of revenue, $847.0 million of Q3’s $895.0 million. Advertisers pay per click, per thousand impressions, per video view or a fixed fee, and contracts typically run less than 30 days, so ad revenue is resold every quarter rather than locked in. Targeting by community, where users have already declared their interests, is the core of the product. Page 7 of the letter says video ad revenue more than doubled in Q3 and that more than 20 million business decision-makers come to Reddit, and the company has expanded lead generation tools for B2B advertisers.
- Reddit is also broadening its advertiser base. The 10-K describes a push from endemic verticals with the most active communities, such as technology and communications, business, legal and finance, and media and entertainment, into automotive, retail, consumer packaged goods and pharmaceuticals. The Q3 letter cites strength in the lower funnel and in travel and B2C services. Reddit Max campaigns, which automate campaign setup, went to general availability with API access, and Reddit Community Intelligence turns billions of posts and comments into marketing insight for brands.
- Other revenue was $48.0 million (+34.8%). The 10-Q describes it as content licensing plus products sold directly to users, such as Reddit Premium and Reddit Gold, which are not material. Licensing customers buy the right to access Reddit content over a contract term. Remaining performance obligations on contracts longer than one year were $62.4 million, mostly long-term content licensing. Nine-month other revenue of $130.0 million is about a seventeenth of advertising.
- Licensing and search traffic share a root. The 10-Q risk factors ask whether the availability of Reddit data from third-party sources hurts both user traffic and the value of licensing deals, and list whether to sign new deals or renew existing ones as a strategic call. The more search engines and AI tools summarize Reddit posts, the fewer people click through, and the more the value of that data has to be captured by contract.
- Geographically, 80.3% of Q3 revenue came from the US and 19.7% from abroad. International DAUq of 79.6 million exceeds the US base, but at $2.43 of ARPU each added international user brings in about a sixth of what a US user does.
- The cost base is light. Gross margin is 91.5%, Q3 capex was about $1 million, and operating cash flow of $363.8 million became $362.6 million of free cash flow. Research and development of $263.5 million (+34.2%) and sales and marketing of $209.4 million are the largest expenses, and full-time headcount was 2,555 at the end of 2025. Q3 GAAP operating income was $261.6 million, a 29.2% margin.
- The next step is logged-in Reddit. The letter says moving to primarily logged-in will add signals for ad targeting, raise engagement, protect access to Reddit’s data and help with emerging regulation, and notes that “Pretty much all of the major ad-based platforms have gone through this transition”. The trade-off is a smaller logged-out count in exchange for better targeting and tighter control over data access.
Reddit vs Meta Pinterest and Snap
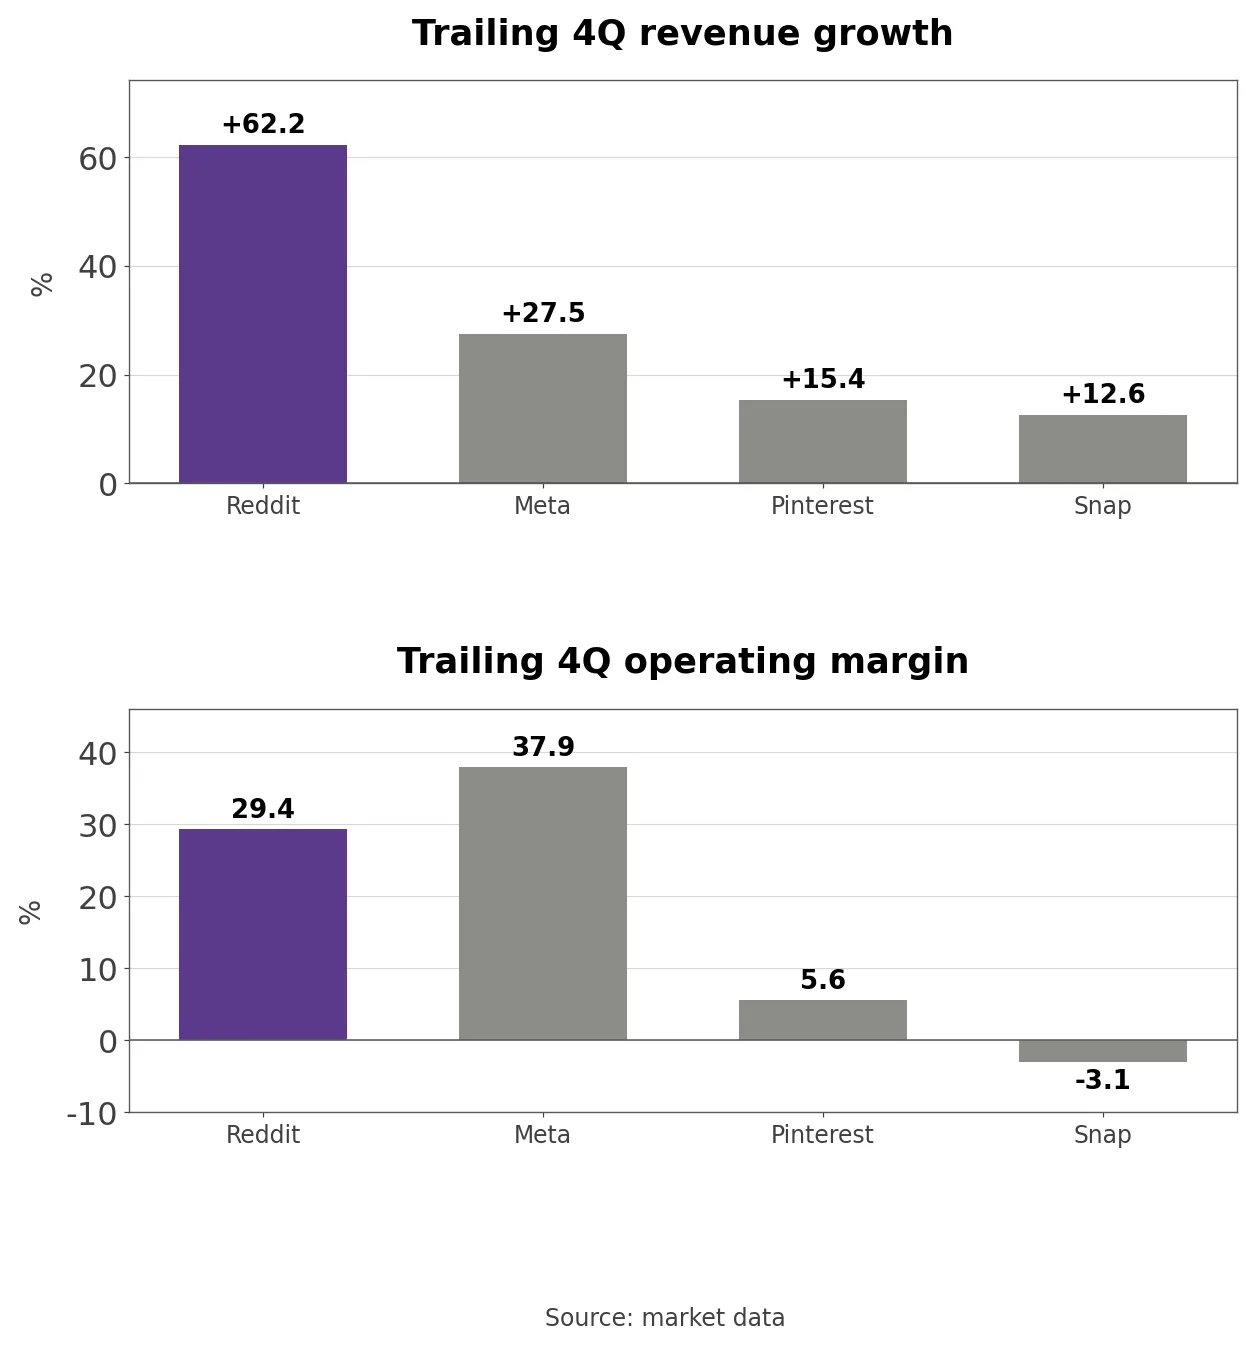
- On market data, TTM revenue growth was +62.2% at Reddit, +27.5% at Meta, +15.4% at Pinterest and +12.6% at Snap (through June). Operating margins were 37.9% at Meta, 29.4% at Reddit, 5.6% at Pinterest and -3.1% at Snap, so Reddit grows fastest and ranks second on margin.
- All four are worth less than a year ago. Reddit’s market value fell -55.1%, against -50.2% at Pinterest, -31.0% at Snap and -16.7% at Meta, so the fastest grower lost the most value.
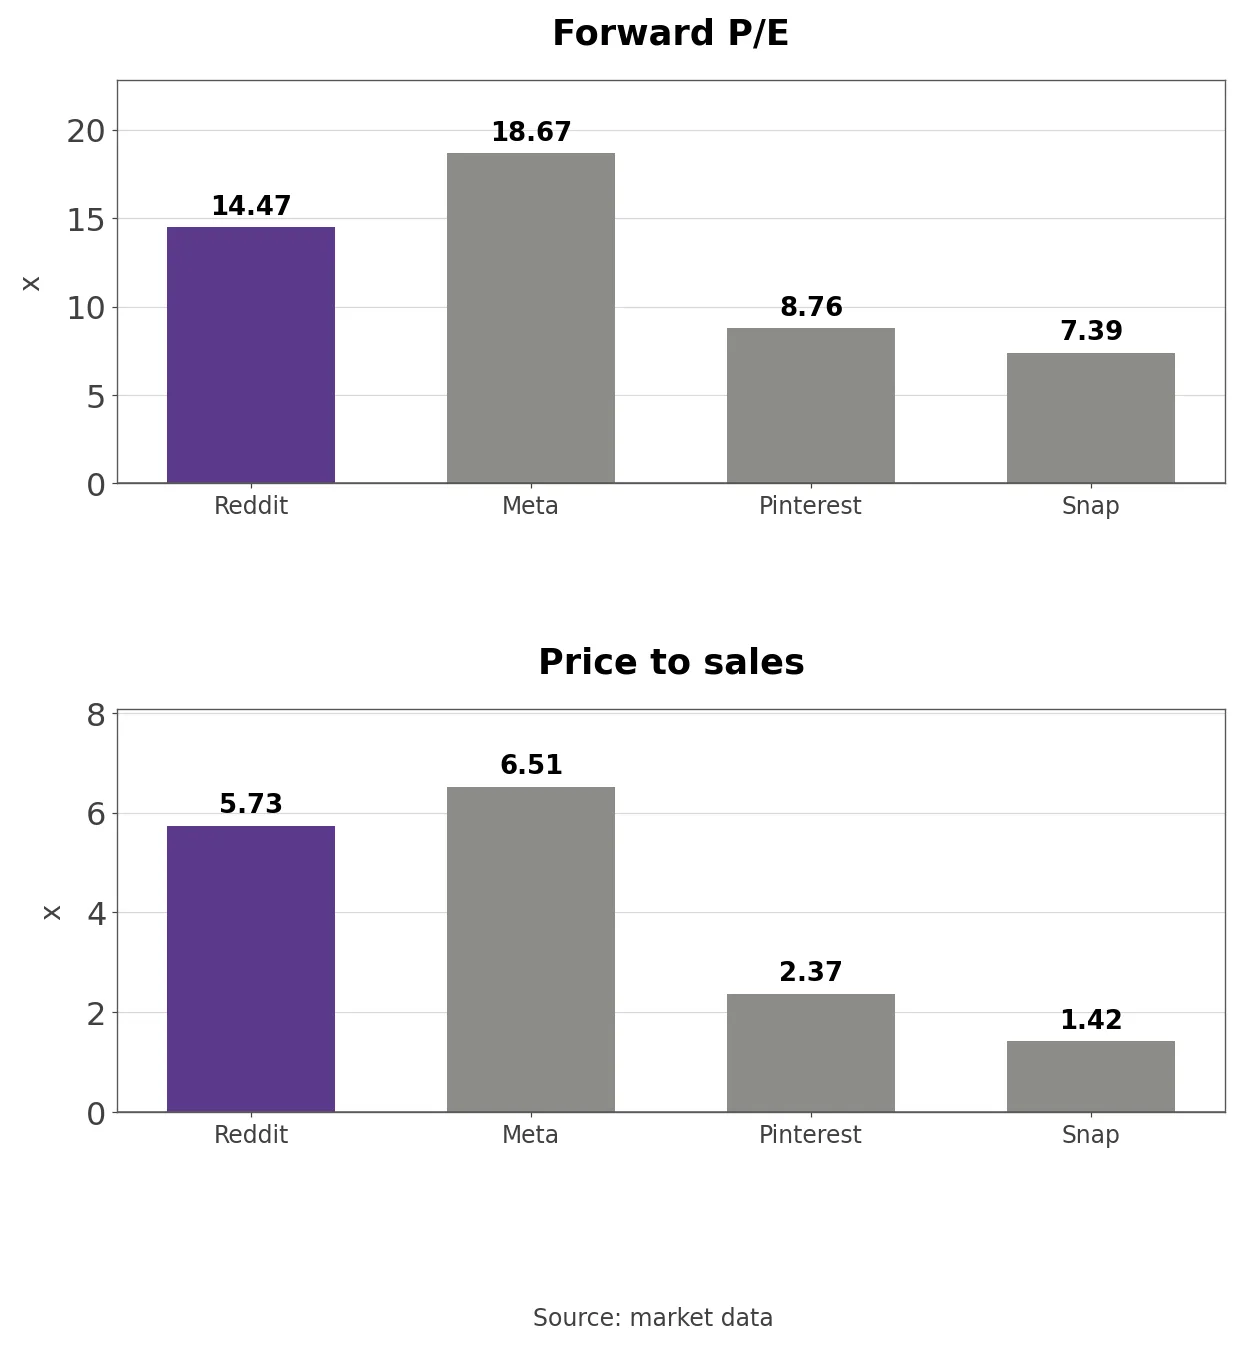
- Reddit’s forward P/E of 14.47 is below Meta’s 18.67 and above Pinterest’s 8.76 and Snap’s 7.39. Its price to sales of 5.73 trails Meta’s 6.51 and is 2.4 to 4.0 times Pinterest’s 2.37 and Snap’s 1.42. Meta, Pinterest and Snap mostly sell ads to logged-in app users built around friends, saved images or messaging. With 58.9% of its DAUq logged out, Reddit is more exposed to changes in search, which helps explain a forward P/E below Meta’s despite more than twice its growth.
Reddit’s Price-to-Sales and EV-to-EBITDA Band
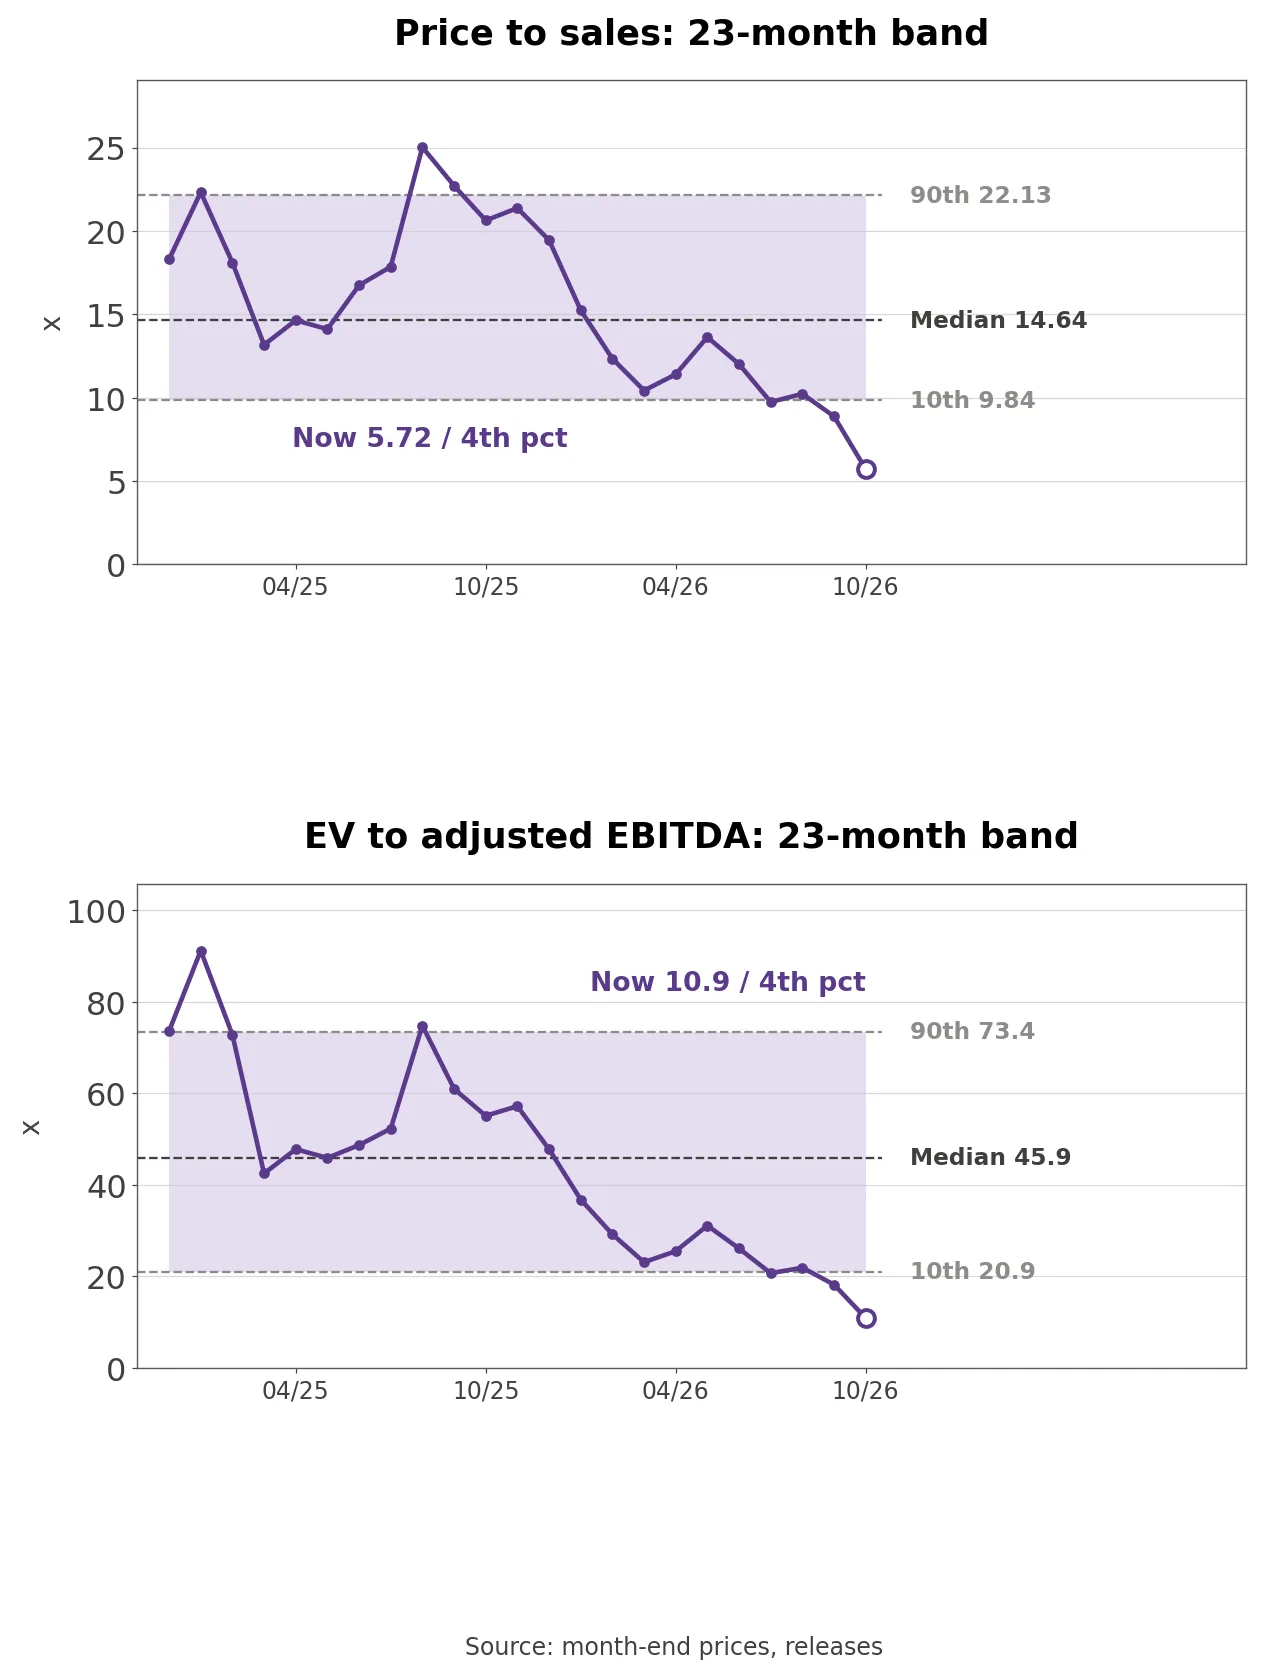
- The band covers 23 months from December 2024, the first month with four post-IPO quarters of adjusted EBITDA. P/E is left out because trailing GAAP net income only turned positive in Q1 2025; market data puts the trailing P/E at 18.73 and the forward P/E at 14.47.
- Own calculation (month-end prices and 11 earnings releases): Price to sales of 5.72 is the lowest of the 23 months (4th percentile, median 14.64, high 25.02). Enterprise value of $14.63 billion, after $3.033 billion of cash and securities, is 10.9 times TTM adjusted EBITDA of $1.338 billion, also a 23-month low (median 45.9, high 91.2).
- Both multiples hit bottom because the stock fell while revenue and profit grew. Swapping the $495 million midpoint of Q4 adjusted EBITDA guidance in for Q4 2025 gives four quarters of $1.506 billion and an EV multiple of 9.7. The price now reflects doubt about how long the profit lasts more than its size.
Three Conditions That Move the Stock
- US logged-in DAUq shows whether the monetized core is holding. If it stays around 23.4 million through the Q4 search decline and starts to grow after the logged-in tests, a falling DAUq count need not reach revenue. A drop in logged-in users as well would hit the base that drives most monetization.
- US ARPU measures how fast pricing covers user losses. Q4 global ARPU of $8.53 or more meets guidance, and US ARPU growth comfortably above the user decline in 2027 would support the stock. Another beat below 3%, or Q4 revenue under the $1.0 billion low end, would weigh on it.
- Sales and marketing as a share of revenue is the price of buying users. A ratio falling from 23.4% while DAUq grows again shows marketing paying off. A rising ratio alongside falling DAUq would stall margin expansion.
What to Watch in the December Quarter
- The Q4 report, likely in early February 2027, should show whether the DAUq decline stays within the low double digits management flagged, whether revenue clears the $1.000 billion to $1.030 billion range and whether US logged-in DAUq held. Whether the company keeps reporting the logged-in and logged-out split is worth watching too.
- One question stays open. Management wants a logged-in Reddit for better targeting, yet logged-out users are 58.9% of DAUq. When the tests outside the US report back, will Reddit accept a smaller DAUq count for higher ARPU, or narrow the rollout?
Related Analysis
- TSMC (TSM) Stock: 60% Margins and Guidance It Keeps Beating: another long streak of beating the company’s own guidance, useful for comparing the size of each beat with Reddit’s narrowing margin over the top of its range.
- Uber (UBER) Stock Analysis: Gross Bookings vs Revenue Gap: a consumer platform where usage and revenue grow at different speeds, a parallel to Reddit’s split between users and ARPU.